All Categories
Featured

Smart Wealth Security with Modern Life Insurance
Table of Contents
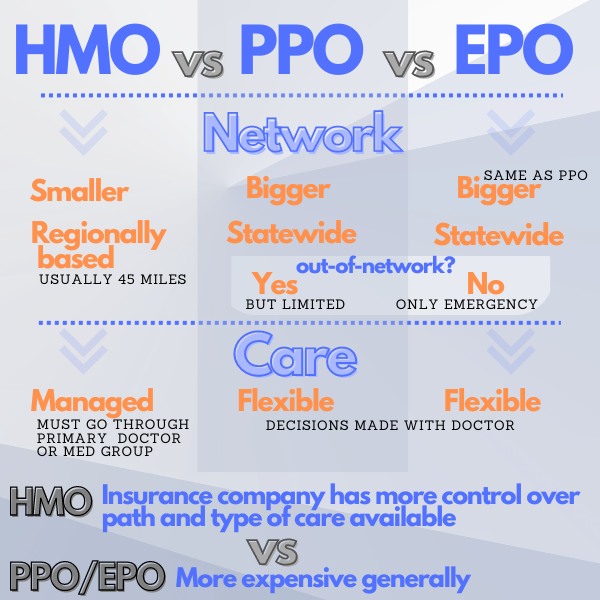
Premiums are typically lower for HMO plans, and there is generally no deductible or a low one. Some HMO strategies, consisting of those used by Medical Mutual, do not need you to pick a PCP or have a recommendation to see an expert. For more HMO specifics, read our About HMO Plans article.
They also feature a network of providers, however there are less restrictions on seeing non-network companies. In addition, your PPO insurance coverage will pay if you see a non-network supplier, although it may be at a lower rate. Here are some crucial functions: You can see the physician or expert you 'd like without having to see a PCP first.
Your benefits will be better if you remain in the PPO network. Premiums tend to be higher, and it's typical for there to be a deductible. Check out a more in-depth meaning of PPO in our PPO Plans short article. As pointed out above, Differences in between HMO (Health Care Organization) and PPO (Preferred Service provider Company) plans include network size, ability to see specialists, expenses, and out-of-network coverage.
Securing Burial Insurance for Families
PPOs normally use greater versatility in seeing specialists, have bigger networks than HMOs, and provide some out-of-network coverage. Here are the comparison points in more detail. A defining feature of HMO and PPO plans is that they both have networks. Networks are one way to lower healthcare expenses network suppliers agree to provide discount rates in exchange for access to a health strategy's members.
In basic, PPO networks tend to be more comprehensive, consisting of more physicians and medical facilities than HMO plans, offering you more option. Nevertheless, networks will differ from insurance provider to insurer, and plan to plan, so it's best to research each strategy's network before you choose. Many HMOs will require you to select a medical care doctor, who will be the primary point of contact for your treatment.
Costs for experts will not be covered without a PCP recommendation. In contrast, PPOs tend not to require selection of a PCP, and you can generally see an expert without a referral, and still have actually these costs covered. For both PPO and HMO strategies, your costs for care will be lowest if you get it from in-network providers.
For HMOs, out-of-network services are generally not covered at all, except for emergency situations. PPOs differ from HMOs because PPO strategies will normally provide some coverage for these kinds of services, however coverage for in-network companies will be better. The extra coverage and flexibility you receive from a PPO suggests that PPO strategies will usually cost more than HMO plans.
Insurance in Oxnard CAHow to Find Best Medicare Supplement Coverage
This is the amount of health care costs you need to pay before your strategy begins to cover your costs. Not all HMOs have deductibles, however when they do, they tend to be lower than PPO deductibles.
49% of covered employees had PPO plans in the survey, while HMOs covered 16%. When it comes to your own health strategy choice, it may sound like a cliche, however when choosing in between an HMO or PPO strategy, it is not necessarily about which is better, however which is best for you.
If your financial situation determines that cost is most important, you may seriously think about choosing an HMO strategy. Normally speaking, costs for HMO strategies will be less. Premiums tend to be lower, and deductibles will also be lower, or might be missing totally. The compromise will be versatility, however.
Insurance in Oxnard CA
Unlike the majority of HMO health insurance, you won't likely need to select a medical care doctor, and you won't typically require a recommendation from that doctor to see an expert. A PPO network will likely be bigger, providing you a higher choice of in-network doctors, experts, and facilities to select from.
Securing Burial Insurance to Support Families
With HMOs, out-of-network protection will usually be limited to emergencies; non-emergency services are not typically covered at all. To assist you weigh the pros and cons described above, here's a fast summary of them: With any strategy, inspect the service provider network to see if your favored suppliers remain in the strategy's network, since remaining in-network will save you money.
You might discover that the specific HMO strategy you're considering includes your preferred suppliers, or at least enough of them to fulfill your needs.

Latest Posts
Smart Wealth Security with Modern Life Insurance

Finding Low-Cost 2026 Family Health Insurance
Getting Private Medical Rates